Greg Castle had been in Luxembourg for 24 hours when the conversation turned to drones. Not what he calls “exquisite systems” costing tens of millions of dollars, but machines priced at “$10.000, $15.000”.
“What’s happened in the Ukraine has really woken us as a nation, the US, and the global community to the fact that warfare has completely changed,” said Castle, founder and managing partner of Anorak Ventures, a California seed investor. Defence, he admits, is “a bit frothy at the moment”. Valuations are high. “But I think it’s for good reason.”
It was his first visit to the Grand Duchy, but Luxembourg money is already in his business. For Anorak’s third fund, which focuses on defence, critical infrastructure and manufacturing, the firm brought in its first European backer: Luxembourg’s Mangrove Capital Partners.
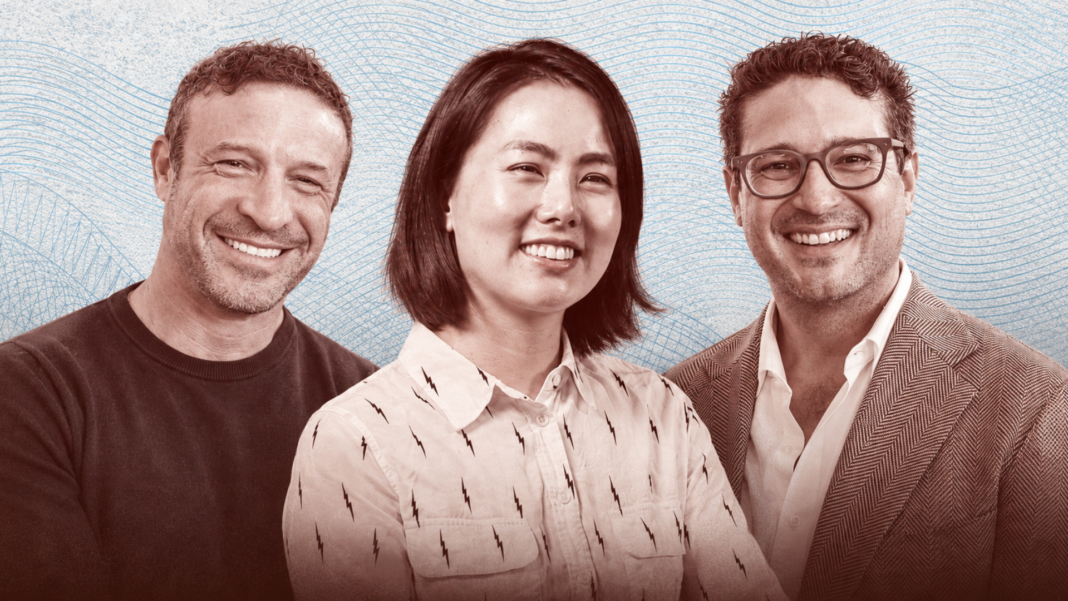
Castle was one of several US investors at the fourth Luxembourg Venture Days this week, and their message was consistent. After a decade in which software absorbed most of the industry’s money, venture capital is moving into the physical world: robots, factories, defence and the supply chains behind them. For Europe’s largest fund centre, the question is whether it can turn that shift into deals. Castle’s own fund suggests it already has.
Physical AI start-ups raised $47.4 billion worldwide in the first half of 2026, according to Crunchbase, more than in 2022, 2023 and 2024 combined. Venture investment in humanoid robots passed $11 billion by early October, Dealroom data show, more than double last year’s total. The largest round went to a European company: Germany’s Neura Robotics raised $1.4 billion.
“The AI is moving from being on your screen to being next to you, around you, in the factories that are building your cars,” said Jacob Mullins, managing director at Shasta Ventures, who earlier helped build Microsoft’s BizSpark start-up programme.
Patti Pan, general partner at Solaris Venture Partners, says her newest fund invests only in physical AI and robotics, a choice her Silicon Valley peers questioned a year ago. Language models, she argues, use about 10% of the data that exists. The rest “is in the physical world”.
For years, Castle said, software-only companies attracted “easy money”. Manufacturing, defence and critical infrastructure “three years ago, five years ago, were a lot less sexy”, and that has “shifted pretty dramatically”. His next bet goes deeper into heavy industry: steel, chemicals, rare earths and materials science.
European defence start-ups raised a record $1.8 billion in 2025, more than double the previous year, according to the 2026 European Deep Tech Report. The same report finds
that 70% of late-stage funding for Europe’s deep-tech start-ups comes from investors outside Europe.
“Countries all over the world are looking at building up their own defence capabilities and not necessarily being reliant on companies based in the US,” Castle said. US investors, he added, “are now awake to this as well”.
Mullins sees a role for Luxembourg, citing its fund industry, the MeluXina supercomputer and the chance to push forward EU Inc, the European Commission’s proposal for an optional EU-wide company form that a start-up could set up in under 48 hours for less than €100.
Pan said the first question her team asks founders never changes: “Do you actually want to make money?” Castle looks for founders who can “tell the same story a thousand times with an equal amount of enthusiasm”.
He knows the arithmetic. An early personal cheque into Oculus paid off when Facebook bought the company for about $2 billion in 2014. Most early-stage bets, he said, will not work out. “But the investments that do work out have to work out in a very big way.”
Read more articles:
Bloomberg: The Luxembourg Investment Summit 2026
New Players Set Sights On Luxembourg As Launchpad For European Expansion
