As institutions enter digital assets, Luxembourg is applying familiar fund controls to a market requiring new approaches to custody, valuation and execution.
“Education is very important so that people get rid of the fear and face the facts,” said Ami Nagata, president of LëtzBlock and managing director of Zodia Custody Luxembourg.
The issue was central to the Digital Assets Funds Seminar, held at PwC Luxembourg on 23 September and co-organised by LëtzBlock, 6 Monks, B2C2, PwC Luxembourg and Q Securities. The seminar examined how investors can access crypto through investment funds and how governance, custody and control must adapt to a continuously traded asset class.
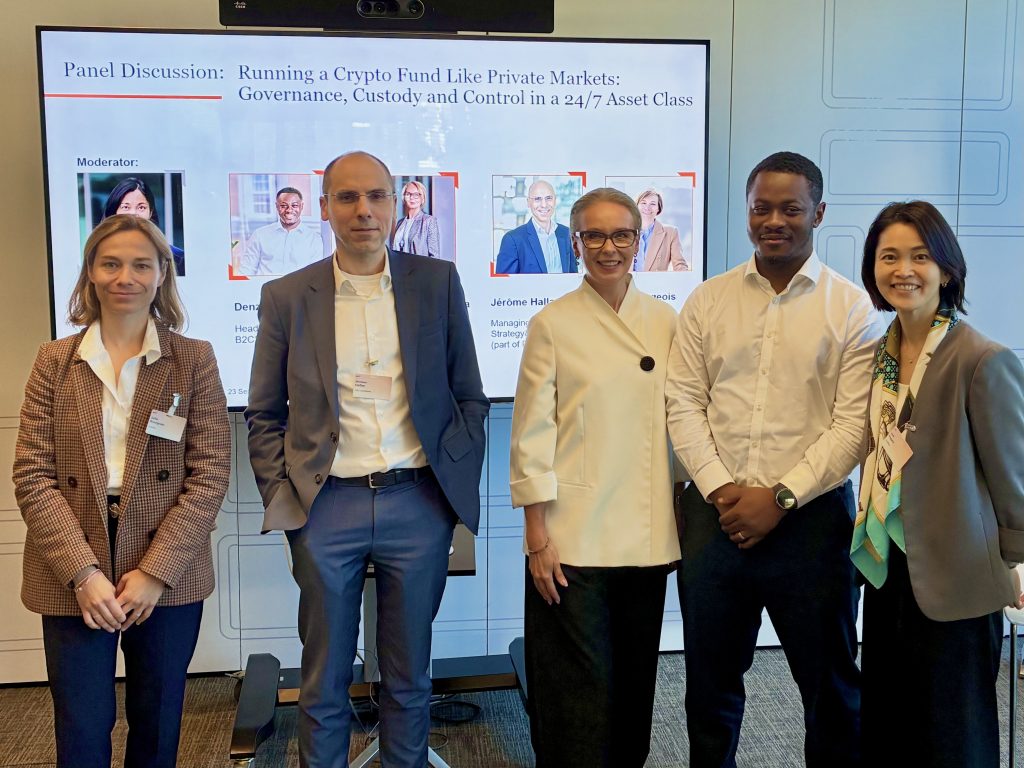
“So far, we have seen this mostly driven from the technology angle, typically led by the head of technology or innovation, whereas it is primarily an ExCo level business problem – given the size of the opportunity. It is about defining the ambition and the strategy, designing the product or service for the target customers, and deciding how it will be distributed and commercialised. It is not because it is crypto or a tokenised fund; it is like any other product or service. What do you want to sell, to whom, through which channel and at what price?” said Jérôme Hallay, managing director at Strategy & Luxembourg.
A credible proposition must explain why a digital asset belongs in a portfolio, whether as a possible hedge against monetary inflation, a source of diversification or a solution to a specific investment problem. Firms that select infrastructure before identifying the customer and commercial purpose risk building products without a clear market.
Assets and Infrastructure
Nagata moderated the panel, beginning with a distinction frequently blurred in discussions about digital finance: the difference between crypto funds and tokenised funds.
“The token is a representation of an asset, whereas crypto is an asset class.”
The discussion drew a clear distinction between the two structures. A crypto fund invests in digital assets such as bitcoin or ether, while a tokenised fund uses blockchain technology to represent fund ownership and potentially automate subscriptions, redemptions and distributions. “The token is a representation of an asset, whereas crypto is an asset class,” said Hallay.
Crypto funds face risks that are either specific to digital assets or amplified by them. Markets operate continuously, liquidity is divided among venues and prices can vary across exchanges. Custody relies on private keys and software.
Institutional crypto funds rely on many of the same participants and controls as traditional alternative investment funds. An authorised alternative investment fund manager oversees the structure alongside the central administrator, depositary, bank, digital-asset custodian, auditor and the venues or liquidity providers through which assets are traded.
“It is the same framework, but different plumbing. This is a market that never sleeps. You still need to put in place a risk-management and compliance framework, calculate the NAV correctly, oversee delegates and ensure the proper safeguarding of assets,” said Julie Bourgeois, head of legal and compliance at 6 Monks.
Continuous trading makes valuation one of the most important operational differences. A fund must establish when its portfolio will be valued, which pricing sources will be used and how discrepancies between trading venues will be resolved. These rules must be documented in advance through the fund’s offering documents and valuation policy.
“You need a very specific cut-off time and a valuation policy that clearly describes how you do things, you must determine which price you use, whether it comes from a single venue or an aggregation of several prices. As the AIFM, we need to demonstrate that we are in control of the valuation method and comfortable with it,” said Bourgeois.
At the chosen cut-off time, the administrator takes a snapshot of the fund’s digital-asset positions, cash balances and applicable market prices. Trading does not stop after that snapshot; subsequent activity instead forms part of the next valuation cycle. This allows the fund to produce periodic reporting while operating within a market that continues trading around the clock.
“The fund needs to stop at some point because you still have to report to investors,” said Bourgeois. A snapshot at that moment, including the prices of the digital assets, the positions and the cash. What happens a second later belongs to the next NAV-calculation cycle.
Control in a Continuous Market
A depositary’s core responsibilities remain the same when a fund invests in cryptoassets. It must monitor cash flows, verify ownership and ensure that transactions comply with the fund’s governing documents and investment policy.
“Our role in digital assets does not change from the traditional role. We oversee ownership and transfers, check whether money has been spent on the correct assets and verify that the fund is being managed in the right way,” said Bogumiła Cebelińska-Woźniak of Q Securities.
The difference lies in the evidence required. Depositaries must reconcile blockchain transactions and wallet addresses with the custodian’s internal records, the fund’s accounting books and its bank accounts. They must also understand who controls the private keys and who is authorised to transfer assets.
“With cryptoassets, we need technological expertise. A blockchain can show that a wallet holds certain assets, but it does not identify the legal owner behind that wallet,” said Cebelińska-Woźniak.
Digital assets add a technological layer to that responsibility. Depositaries must understand wallet structures, transaction hashes, private-key controls and the records maintained by crypto custodians. A blockchain may show that a wallet holds an asset, but additional records are required to connect it to its legal owner and the fund’s accounts.
Liquidity and Settlment
Denzel Walters, head of Luxembourg at B2C2, addressed institutional liquidity and execution. Unlike an exchange order book, a liquidity provider can offer a firm price before execution and assume the resulting risk on its balance sheet.
“What should happen when you execute with a liquidity provider is that you minimise slippage. You can execute block trades, see a firm price beforehand and verify that execution with your depositary, custodian and AIFM,” said Walters.
Walters also challenged the assumption that blockchain settlement is necessarily less manageable than conventional payments. “On-chain settlement actually has a lot of benefits,” said Walters. Transactions can be monitored and independently verified, although their finality makes controls before execution essential.
Those controls include whitelisting wallet addresses, verifying ownership and introducing delays when settlement instructions change.
Luxembourg’s opportunity does not depend on encouraging speculative crypto trading. Its advantage lies in applying the country’s established fund expertise to digital assets while maintaining the governance, oversight and investor protections expected by institutions.
“I think Europe is going to be very big in tokenised funds, but I question the size of classic crypto funds.”
Education can reduce fear, but technology alone cannot ensure success. Firms must still define their market, client and purpose. “I think Europe is going to be very big in tokenised funds, but I question the size of classic crypto funds,” said Walters.
Read more articles:
ClearSpace Signs ESA Contract To Advance Phoenix GEO Life-extension Mission
Reversible Construction Permits: Rethinking The Way Forward?